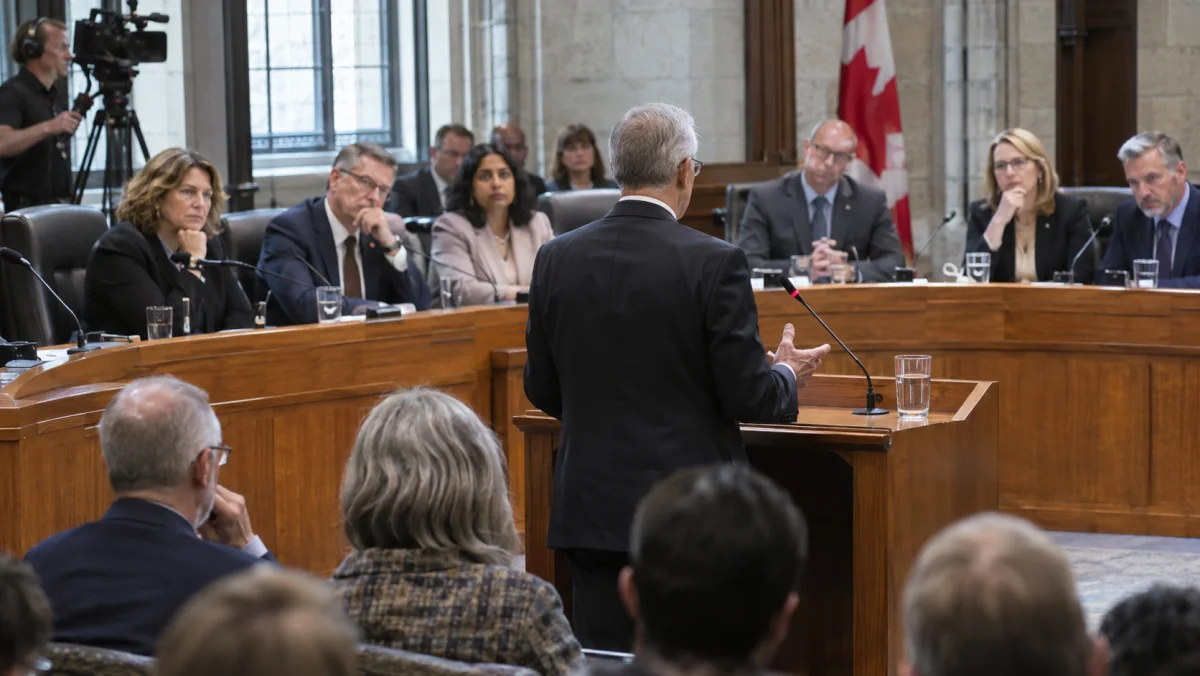
Bank of Canada Governor Tiff Macklem told the House of Commons Standing Committee on Finance on November 3, 2026 that there could be a need to raise the policy rate further, while adding that the Bank would proceed carefully given high uncertainty. The appearance followed the Bank's October 28 decision to lift its policy rate by 25 basis points to 2.5%, its first increase since July 2023.
- Policy rate: 2.5% (raised October 28, 2026)
- CPI inflation around 3% since April; expected to reach about 3½% by year-end
- Inflation projected at or above 3% through much of 2027, near 2% by mid-2028
- Unemployment rate around 6½% for several months
- Next rate announcement: December 9, 2026
What the Governor said
In his opening statement, Macklem gave two reasons for October's increase. First, the inflation outlook has worsened: with the war in the Middle East persisting, oil prices have risen and are expected to stay higher for longer, which shows up at the gas pump and in business costs. Second, the growth outlook has improved modestly. Second-quarter GDP grew 3.3% and recent indicators point to about 2% growth in the third quarter, with consumer spending solid and exports and business investment rebounding.
The statement said businesses have so far absorbed much of the rise in input costs, but that past experience and the Bank's surveys suggest more of those costs will be passed on over the next year. Governing Council judged that inflation risks have increased and there is less scope for monetary accommodation, and it will take future decisions one meeting at a time.
What it means for borrowers
Our interpretation: The message is that October's hike may not be the last, but no further move is committed. That keeps the December 9 decision open in both directions.
- Variable-rate and HELOC borrowers are the first affected by any change, since their rates usually follow lenders' prime rates, which tend to move with the policy rate.
- People renewing or buying on a fixed rate are more exposed to bond yields, which react to inflation expectations and to signals like this one.
- Savers may see deposit rates hold up while the Bank keeps a tightening bias.
What to do next
Variable-rate borrowers can review the steps in the variable-rate checklist after a rate hike and test a higher rate with the fixed vs variable calculator. Anyone with a renewal in the next few months can ask a lender or a mortgage broker about a rate hold, and should compare the full offer, not only the headline rate.
Sources
- Bank of Canada, Opening Statement before the House of Commons Standing Committee on Finance, 2026-11-03. Accessed 2026-11-05.
- Bank of Canada, Parliamentary Appearance by the Governor and the Senior Deputy Governor of the Bank of Canada, 2026-11-03. Accessed 2026-11-05.
- Bank of Canada, Upcoming events, accessed 2026-11-05.
This news summary is general information, not financial advice. Rate outlooks can change quickly; speak with a licensed mortgage professional about your own situation.