Mortgage and Industry Professionals

Commercial mortgage brokers in Canada

A commercial mortgage is secured against property held to produce income rather than to live in, retail, office, industrial, multi-unit residential and mixed-use. The lender underwrites the building's income first and the borrower second, which is the fundamental difference from a residential application.

The brokers listed here arrange commercial mortgages and commercial real estate loans across Canada. Terms are negotiated rather than posted, so who presents the file, and how, changes the outcome more than it does on a house.

The brokers below have told us they take on commercial files. Narrow by city to see who works in your market, most lending decisions still turn on where the property sits.

Where these brokers work from

5 of these brokers have a mapped office. Tap a pin to open that profile.

Arsalan ToufighjouClaimed, Claimed by the owner on 2026-09-10: email and mobile confirmed by one-time code. Licence and other details are self-reported.
Mortgage Broker · Miracle financial
Financial Services Regulatory Authority of Ontario (FSRA)FSRA#22000435

I’m a mortgage broker and co-founder of Miracle Financial, helping homeowners and buyers across Ontario find practical mortgage solutions. A large part of my work involves refinancing, debt…
RefinanceDebt consolidationPrivate mortgageReverse mortgageGuelph, London +3
Lakhvir LallClaimed, Claimed by the owner on 2026-10-14: email confirmed by one-time code. Licence and other details are self-reported.
Principal Broker · Admire Mortgage Group - Mortgage Architects
Financial Services Regulatory Authority of Ontario (FSRA)FSRA#M16001565

As Licensed Principal Broker, I’m dedicated to providing you with all the information you need to make a well-informed decision on your mortgage financing needs. My mortgage industry knowled…

Self-employedFirst-time buyerPrivate mortgageConstructionBurlington, Calgary +3
Nima SabetClaimed, Claimed by the owner on 2026-09-14: email and mobile confirmed by one-time code. Licence and other details are self-reported.
Mortgage Agent Level 2 · Sherwood Mortgage Group
Financial Services Regulatory Authority of Ontario (FSRA)FSRA#M17001730

With 10 years of extensive, hands-on experience in the Canadian mortgage industry, your agent specializes in turning complex financial scenarios into clear, actionable pathways. Providing co…

Self-employedFirst-time buyerDebt consolidationPrivate mortgageKitchener, Markham +3
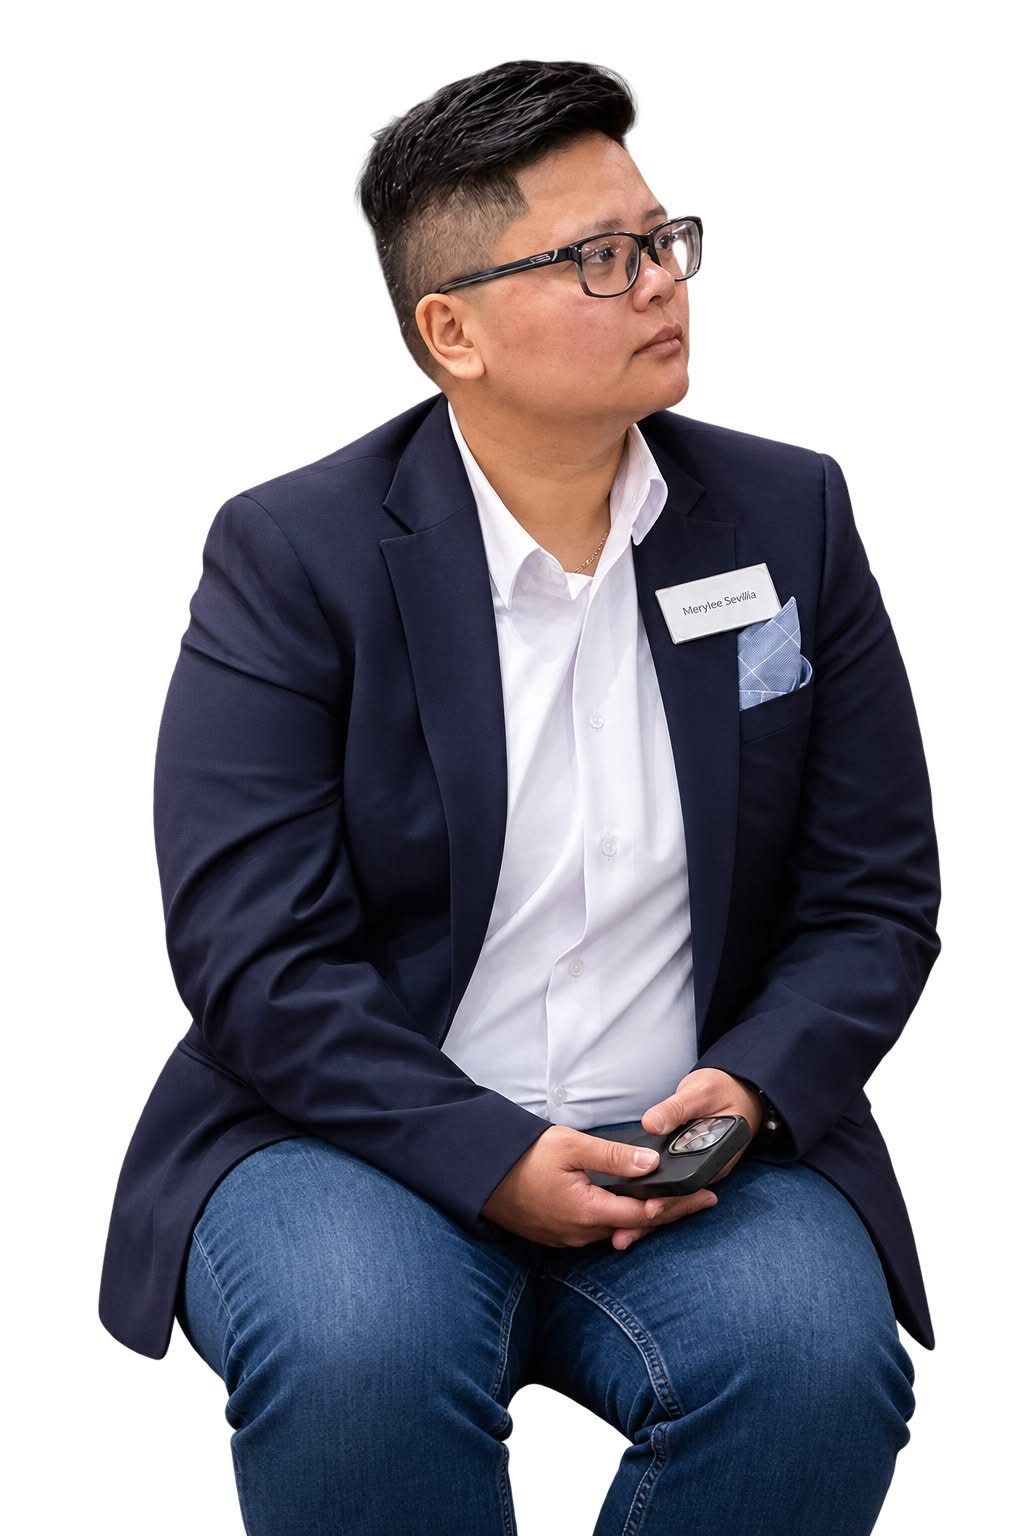
Merylee SevillaClaimed, Claimed by the owner on 2026-09-14: email and mobile confirmed by one-time code. Licence and other details are self-reported.
Mortgage Agent Level 2 · Get a Better Mortgage
Financial Services Regulatory Authority of Ontario (FSRA)FSRA#M22003357

I’m a Level 2 Mortgage Agent with Get A Better Mortgage, serving residential clients in Ottawa and commercial clients across Ontario. Known as the “Mortgage Matchmaker,” I connect borrowers…

Self-employedNew to CanadaFirst-time buyerRefinanceMississauga, Oakville +3
Jermaine AndersonClaimed, Claimed by the owner on 2026-10-13: email confirmed by one-time code. Licence and other details are self-reported.
Mortgage Agent Level 2 · Bay Hill Financial
Financial Services Regulatory Authority of Ontario (FSRA)FSRA#M21002754

As a Level 2 Mortgage Broker serving clients across Ontario, I help individuals, self-employed professionals, investors, and business owners secure financing tailored to their needs. My serv…

RefinancePrivate mortgageConstructionReverse mortgageAjax, Mississauga +3
Nadia MeyerClaimed, Claimed by the owner on 2026-10-20: email confirmed by one-time code. Licence and other details are self-reported.
Mortgage Agent Level 1 · BRX Mortgage
Financial Services Regulatory Authority of Ontario (FSRA)FSRA#M25002920

With over 13 years of experience in financial services, I help homebuyers, homeowners, and self-employed professionals navigate mortgage financing with confidence. Specializing in residentia…

Self-employedNew to CanadaFirst-time buyerMortgage renewalToronto
P.Michael ThomasClaimed, Claimed by the owner on 2026-09-10: email and mobile confirmed by one-time code. Licence and other details are self-reported.
Mortgage Broker · The Mortgage Alliance Company of Canada
Financial Services Regulatory Authority of Ontario (FSRA)FSRA#M12002236

I'm P. Michael Thomas, AMP, Mortgage Broker, helping homebuyers, homeowners, investors and business owners find practical mortgage and financing solutions. With almost 10 years of experienc…

Self-employedFirst-time buyerRefinanceDebt consolidationAjax, Markham +3

How commercial lending is underwritten

The central measure is the debt service coverage ratio, the property's net operating income divided by its annual debt payments. Lenders want a cushion above 1.0, and the required cushion rises with the perceived risk of the asset class and the tenant covenant.

Loan-to-value limits are lower than on residential, and vary sharply by property type. Multi-unit residential is treated most favourably, and there are federal insurance programs for purpose-built rental that improve terms substantially where a project qualifies.

What differs from a residential mortgage

Terms are shorter and amortisations often longer, which leaves a balance outstanding at maturity that has to be refinanced. Rates are quoted per deal rather than posted. Personal guarantees are common, and whether the loan is recourse or non-recourse is negotiable and consequential.

Fees are also structurally different: expect an application or commitment fee, and appraisal, environmental and legal costs that are yours whether or not the deal completes. Budget for them at the outset.

Common questions

What is a commercial mortgage?

A loan secured against income-producing property, retail, office, industrial, multi-unit residential or mixed-use. The lender assesses the property's income and the strength of its tenants before it assesses the borrower, which is the main difference from a residential mortgage.

What are commercial mortgage rates in Canada?

They are quoted per deal rather than posted, and sit above residential rates. Pricing depends on the asset class, the debt service coverage ratio, the loan-to-value, the lease profile and the borrower's experience. Two similar buildings can price quite differently on tenant quality alone.

How much down payment is needed for a commercial property?

More than residential, and it varies by property type. Multi-unit residential is treated most favourably; specialised or single-tenant properties require the most. The figure follows the loan-to-value the lender will accept for that asset class, not a fixed percentage.

What is a debt service coverage ratio?

Net operating income divided by annual debt payments. A ratio of 1.0 means the property exactly covers its financing; lenders require a cushion above that, and the size of the cushion rises with the risk of the asset class. It is the single most important number in a commercial application.

Can you get a commercial mortgage for a multi-unit residential building?

Yes, and buildings above a certain number of units are financed commercially rather than residentially. Multi-unit residential generally receives the best commercial terms available, and federal insurance programs for purpose-built rental can improve them further where a project qualifies.

Commercial by city